
Key Market Insights
Market Overview At A Glance
Total Sales October 2025
10,708
Units
YoY Oct Market Growth
+12.9%
(9,481 sales in Oct 2024)
Highlight 1
Toyota Dominates With Over 3,000 Units, Highest Sales Month YTD
Highlight 2
Tesla and BMW Drive Luxury Segment Decline
October 2025 New Vehicle Market Summary – New Zealand
Key Highlights from October 2025
Toyota soars to 3,232 units, outselling Mitsubishi by over 2,000 cars, driven in part by the dominance of the RAV4, which single-handedly outsold all Mitsubishi passenger cars combined by 486 units.
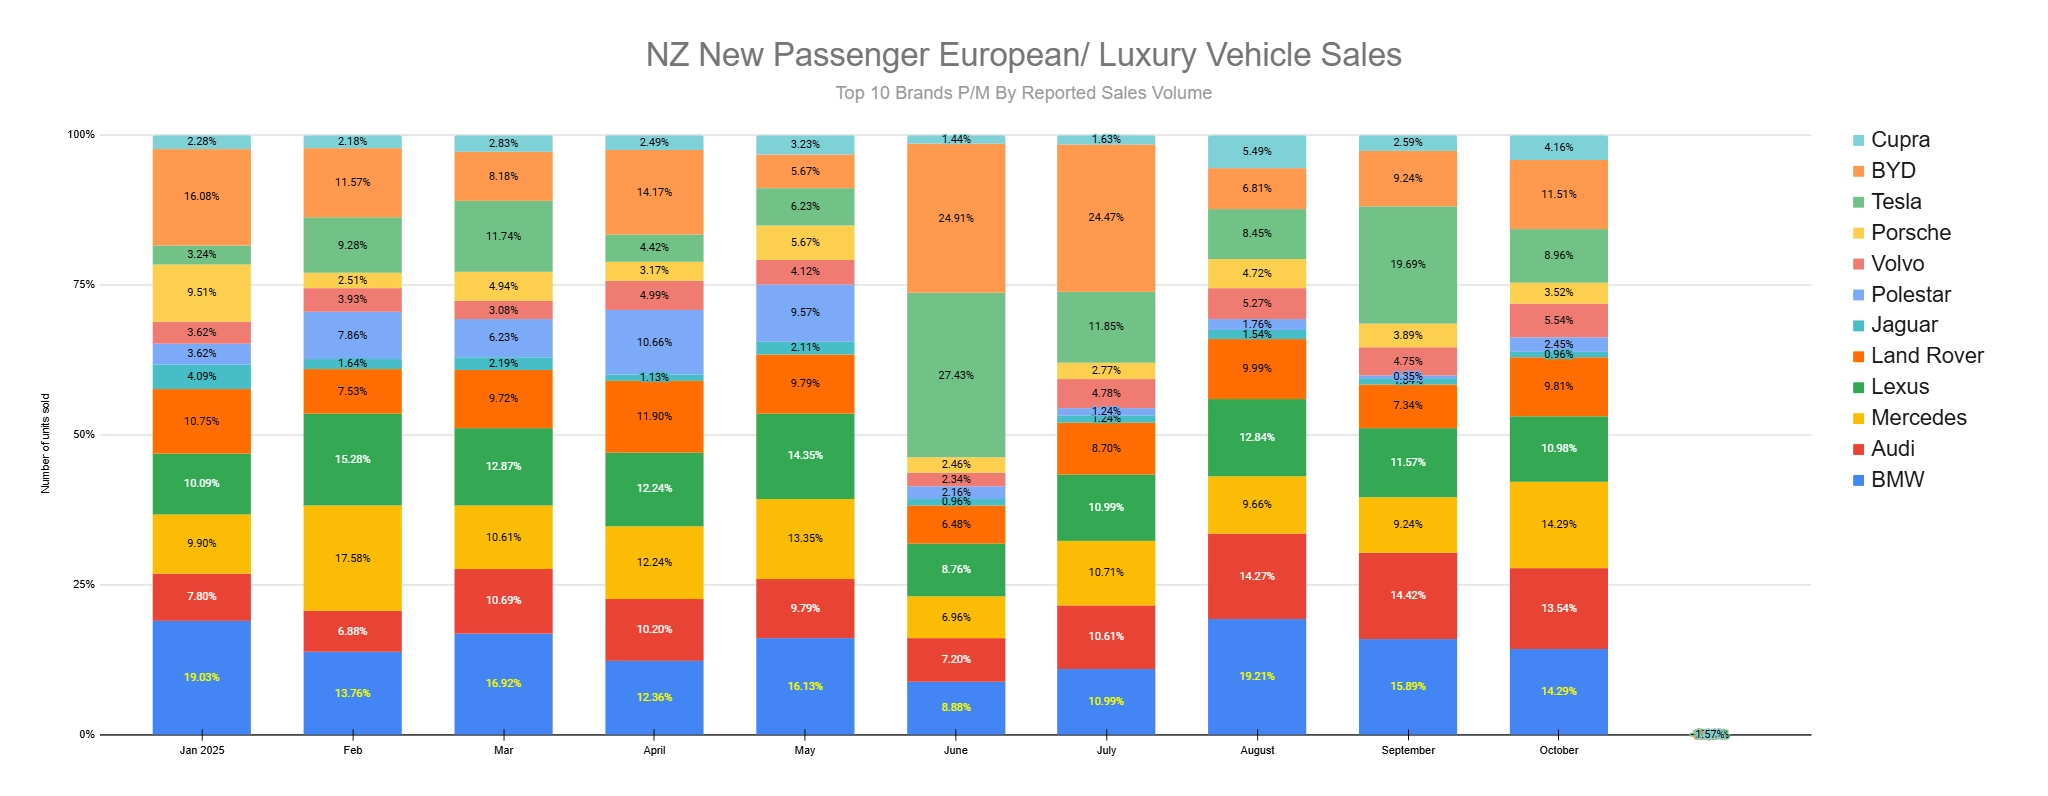
Tesla leads luxury market decline, accounting for 65% of the MoM drop in the European segment, while BMW also fell by 50 units. Together, these two brands erased nearly 90% of the luxury segment’s month-on-month losses.
October Overall Market Summary
Despite headline gains in the volume segment, New Zealand’s total new vehicle market grew by just 32 units in October, signalling a stall in upward momentum as we move deeper into Q4. The volume segment drove nearly all of October’s gains, lifting by +340 units MoM, thanks to Toyota’s massive 812-unit spike, supported by Ford, Mazda, and Hyundai. However, these gains were nearly wiped out by a -220 unit decline in the luxury segment, with Tesla and BMW alone accounting for 88% of that drop. The EV/new-brand segment also softened, down -88 units MoM, led by a contraction in Tesla and BYD registrations, partially offset by another record-breaking month for Chery. Overall, October marked a market-wide plateau: while mainstream brands saw renewed traction, declines in higher-margin segments may affect dealer profitability and finance conversion rates. The broader outlook heading into November will hinge on retail offers, stock levels, and early Christmas campaign activity.
October Segment Breakdown
Volume segment: Momentum Meets Volatility
October marked another milestone in what has become a record-setting year for new vehicle sales across New Zealand. Total B2C registrations climbed by 340 units month-on-month in the volume segment, reaching 8,978, the highest monthly figure of the year for the volume segment.
- Toyota’s Return to Form
At the center of this surge was Toyota, which posted a staggering 3,232 sales in October, a +812 unit gain vs. 2024, and +668 units MoM over its already strong September showing. To put that in perspective, Toyota’s market share for the month swelled to 36% of the volume segment, eclipsing the combined total of Kia, Mitsubishi, and Hyundai. The Toyota RAV4 remains the central driver of this dominance, with internal figures showing it outsold all of Mitsubishi’s range by nearly 500 units. - Mitsubishi Slides from September Peak
After an unprecedented sales spike in September (1,755 units), Mitsubishi pulled back to 1,151 units in October. While this is still its second-highest month in 2025, it’s a 604-unit MoM decline, eroding much of the gain seen in September. MoM performance across the rest of the Japanese cohort was mixed, Mazda (+44 units) and Hyundai (+191 units) gained ground, while Kia (-102 units) and Suzuki (-63 units) lost steam. - Ford Grows Quietly, But Decisively
Ford saw its best month of 2025, pushing 660 units, up +245 MoM and +18 YoY, lifting its market share to 7.35%, the highest since May. While it lacks the headline-grabbing spikes of Toyota or Tesla, Ford’s slow but steady climb warrants attention, especially if it can maintain momentum across Ranger and Everest sales.
European & Luxury: Tesla & BMW Drive a Segment Retreat
The luxury segment cooled slightly in October, down 220 units from September, representing an 8.76% share of the total market — the lowest since April.
Two brands were responsible for the bulk of the contraction:
- Tesla (-144 units): Reversed its strong September performance, accounting for 65.5% of the entire luxury market’s MoM decline.
- BMW (-50 units): Represented 22.7% of the overall luxury drop, moving from 184 units to 134.
While some brands did gain, including Mercedes (+27), Polestar (+19), and BYD (+1), their minor lifts couldn’t offset the weight of Tesla’s and BMW’s pullback.
Lexus, Audi, Porsche, and Jaguar also posted modest MoM declines, contributing to a fragmented and cautious luxury outlook as we head toward year-end.
EV & New Energy Brands: A Battle for Share
October saw a modest drop of 88 units MoM across the EV and new brand segment — though this was still the third-highest month for this cohort in 2025. Chery’s performance was the standout, delivering 259 units, representing 38.6% of the EV/new brand segment alone.
- Chery Leads the Pack, Again
With consistent performance now for four consecutive months, Chery has rapidly become the dominant Tier-2 EV brand behind BYD and Tesla. Its momentum has been key in stabilizing the segment despite drops from Tesla (-144) and BYD (-1). - Leapmotor, JAECOO & Omoda Stay Consistent
Leapmotor (+3), Omoda (+13), and JAECOO (+29) continue to build awareness and scale slowly. Though they’re far from market-share leaders, their double-digit monthly outputs indicate strong dealer and marketing performance in their respective niches.
Strategic Recommendations for NZ Dealerships
- Stock Toyota RAV4s and reinforce Toyota used inventory, the brand’s dominance will continue to drive showroom traffic and trade-ins.
- Monitor Mitsubishi inventory closely, September’s spike appears to be a short-term anomaly; ensure pricing is aligned to demand.
- Capitalize on Ford’s steady climb, promote Ford’s diverse offering, especially to conquest Mitsubishi and Suzuki intenders.
- Reassess luxury channel mix, BMW and Tesla’s volatility could impact pipeline forecasting. Consider boosting Polestar, Mercedes, and Volvo inventory.
- Ride the Chery wave, with 259 units in October, this is no longer a fringe brand. Integrate Chery into your digital and in-store marketing.
- Support new energy brands early, Omoda, Leapmotor, and JAECOO are building mindshare. Get ahead of demand to secure margin before competitors catch on.
October 2025 Marketing Recommendations
- Volume Segment
- Strategic Focus: Scale efficiency, loyalty targeting, and competitor conquest
- Toyota: Leverage momentum – Toyota’s enormous gain positions it to dominate the holiday cycle. Run CRM-based loyalty ads for RAV4 and Hilux with hybrid trade-in messages.
- Ford & Mazda: Conquest Mitsubishi owners – Use Mitsubishi’s 604-unit MoM decline as a signal to target defecting buyers, particularly from ASX and Eclipse Cross, with SUV upgrade ads.
- Kia & Hyundai: Price-per-feature messaging – As both brands saw modest shifts, run “better spec for the price” messaging to defend against MG and Chery in crossover segments.
- Luxury/European Segment
- Strategic Focus: Mitigate volatility, elevate service experience, shift Tesla strategy
- Tesla: Rebalance budget to post-lead nurture – With a -144 drop MoM, Tesla marketers should pause new reach efforts and instead retarget past page viewers or leads with exclusive offers or upgrade messaging.
- BMW: Offset October slump with end-of-year bundles – Re-engage high-intent audiences with 0% finance or free servicing creative for X1/X3 buyers.
- Polestar, Lexus, Mercedes: Stability messaging – Promote luxury brands that saw MoM growth as consistent, secure alternatives. Use testimonial-style ads and service satisfaction guarantees to build trust.
- EV & New-Energy Brands
- Strategic Focus: Trust-building, affordability emphasis, education funnel expansion
- Chery: Transition from challenger to contender – Chery’s growth (+34 units MoM) makes it a serious player. Run side-by-side comparisons vs MG ZS EV, and include local testimonials where possible.
- BYD & Tesla: Refocus campaigns on ownership cost – With both brands down MoM, redirect messaging toward running-cost benefits, battery warranty, and in-stock vehicle CTAs.
- Emerging brands (Omoda, Leapmotor): Push awareness retargeting – Use video-first sequences highlighting affordability, 5-star safety (if applicable), and “Why switch?” comparisons to legacy makes.